Home
What Is an Estate and How Does It Work Legally and Financially?
The term "estate" is one of the most versatile words in the English language, carrying significant weight in courtrooms, bank vaults, and real estate offices. At its core, an estate represents the entirety of a person's existence in the eyes of the law and the economy. Whether you are calculating your net worth for a loan or planning how to pass your legacy to the next generation, you are dealing with an estate.
Understanding the nuances of an estate is critical because the rules governing it change depending on the context. In probate law, an estate is a temporary legal "person" created to settle debts. In financial planning, it is a snapshot of your wealth. In history, it was the foundation of social class. This guide explores these dimensions to provide a clear framework for managing, protecting, and eventually liquidating an estate.
Defining the Multi-Dimensional Meaning of an Estate
To understand what an estate is, one must look through three distinct lenses: financial, legal, and physical. Each lens reveals a different set of rules and implications for the owner.
The Financial Snapshot
Financially, an estate is the sum total of an individual's net worth. This includes every asset you own—cash in bank accounts, stocks, bonds, real estate, jewelry, and even your car. However, an estate is not just "stuff." It also includes your liabilities. To find the true value of an estate, you must subtract all debts, such as mortgages, credit card balances, and personal loans, from the total value of the assets. According to Cornell Law School's Wex Definitions , an estate encompasses all property, real and personal, that a person owns.
The Legal Entity
In the legal world, specifically during probate, the estate becomes a distinct entity. When a person passes away, their belongings don't immediately transfer to heirs. Instead, they enter a legal "waiting room" known as the estate. This entity is responsible for paying the deceased person's final taxes and settling with creditors. Only after these obligations are met can the remaining assets be distributed. This process ensures that the transition of wealth is orderly and follows the decedent's wishes or state law.
The Physical Land and Social Context
Historically, the word "estate" referred to a large parcel of land under single ownership. In the British and Irish manor systems, an estate was often a self-sustaining business, generating income through tenant rents and agricultural production. Beyond land, the term also appears in social theory. The "Estates of the Realm" historically categorized society into the clergy, nobility, and commoners. Today, we still hear references to the "Fourth Estate," a term used to describe the news media and its role in providing a check on political power.
What Counts as a Legal Estate During Probate?
When a person dies, not everything they owned necessarily becomes part of their "probate estate." Distinguishing between what goes through court and what transfers automatically is one of the most important steps in estate administration.
The probate estate typically includes assets held solely in the decedent's name. For example, if you own a house alone or hold a bank account without a co-signer or beneficiary, those assets must go through probate. Property held as "tenants-in-common" also enters the probate estate, as the decedent's specific share does not automatically pass to the other owners. Furthermore, if a life insurance policy lists "the estate" as the beneficiary rather than a specific person, those funds are funneled into the probate process to pay off debts or be distributed by the court.
As noted by Cross Law Group , an estate is also a legal obligation. It must settle all liabilities before heirs receive a dime. This means that if an estate has $100,000 in assets but $120,000 in debt, the heirs will likely receive nothing, as the estate is technically insolvent. Understanding this hierarchy of payment is essential for executors who are tasked with managing these competing interests.
Why Some Assets Bypass the Estate Entirely
Many people are surprised to learn that a Will does not control everything they own. In fact, some of your most valuable assets may bypass the probate estate entirely through what is known as "operation of law." These are called non-probate assets.
The Power of Non-Probate Assets
Non-probate assets transfer automatically to a survivor or beneficiary upon the owner's death. Common examples include property held in "Joint Tenancy with Right of Survivorship" (often seen with married couples and their homes) and accounts with "Payable on Death" (POD) or "Transfer on Death" (TOD) designations. Because these assets have a pre-determined path, they do not need a judge's permission to change hands. This can save families months of time and thousands of dollars in legal fees.
Why Titles and Beneficiary Designations Override Wills
A critical friction point in estate planning is the conflict between a Will and a Title. If your Will says your sister should get your 401(k), but your 401(k) beneficiary form still lists your ex-spouse, the beneficiary form wins. The legal title or designation almost always overrides the instructions in a Will. This is why "estate planning" is a continuous process of updating paperwork, not just writing a single document.
| Asset Type | Transfer Method | Goes to Probate Court? |
|---|---|---|
| Solely Owned Home | Will or State Law | Yes |
| Joint Tenancy Home | Operation of Law | No |
| 401(k) / IRA | Beneficiary Designation | No |
| Bank Account (No POD) | Will or State Law | Yes |
| Assets in a Living Trust | Trust Agreement | No |
How Your Estate Represents Your Total Financial Net Worth
While lawyers focus on probate, financial planners focus on the "Gross Estate." This is the total value of everything you have an interest in at the time of your death, regardless of whether it goes through probate. This figure is used to determine if you owe federal or state estate taxes—often referred to as the "death tax."
Calculating the taxable estate involves more than just looking at your bank balance. It includes the fair market value of your real estate, the face value of life insurance policies you own, and the value of personal property like art collections or vintage vehicles. For high-net-worth individuals, the goal of estate planning is often to reduce the size of the taxable estate through gifting or trusts while they are still alive.
Advanced Strategies to Protect and Grow a Large Estate
For those with significant assets, simple wills are often insufficient. Advanced estate planning techniques are used to shield wealth from taxes and ensure it lasts for multiple generations. These strategies are widely regarded as some of the most effective ways to maintain a family legacy.
- The Dynasty Trust: In certain jurisdictions, such as Maryland, a Dynasty Trust can be established to last in perpetuity. This allows assets to grow and be passed down for generations without being subject to estate, gift, or generation-skipping transfer taxes at each death.
- Grantor Retained Annuity Trusts (GRATs): This is a sophisticated move where an individual transfers high-growth assets into a trust for a set term. The individual receives an annuity payment, and at the end of the term, any remaining appreciation in the asset passes to heirs tax-free. As noted by Venable LLP , GRATs are a top-tier option for transferring investment property to the next generation.
- Corporate Recapitalization: Business owners often use this to pass ownership to children without giving up control. By creating voting and non-voting stock, the owner can gift the non-voting shares (the economic value) to heirs while keeping the voting shares (the decision-making power) for themselves.
Why Large Parcels of Land Are Still Called Estates
The term "estate" remains the standard descriptor for significant land holdings. This usage is rooted in the evolution of the manor system. Historically, an estate was the land belonging to a lord, which included the "demesne" (land kept for the lord's own use) and land let to tenants. According to Wikipedia , by the year 1800, there were approximately 4,000 such estates in Ireland alone, each centered around a "big house."
In modern times, these estates have transitioned from feudal holdings to corporate entities. In cities like London, "Great Estates" like the Grosvenor Estate still own vast swaths of urban land, functioning as sophisticated real estate investment and management firms. In the world of Commercial Real Estate (CRE), the "estate" concept is tied to the capital stack—the layers of financing (debt and equity) that allow these massive properties to be bought, sold, and developed.
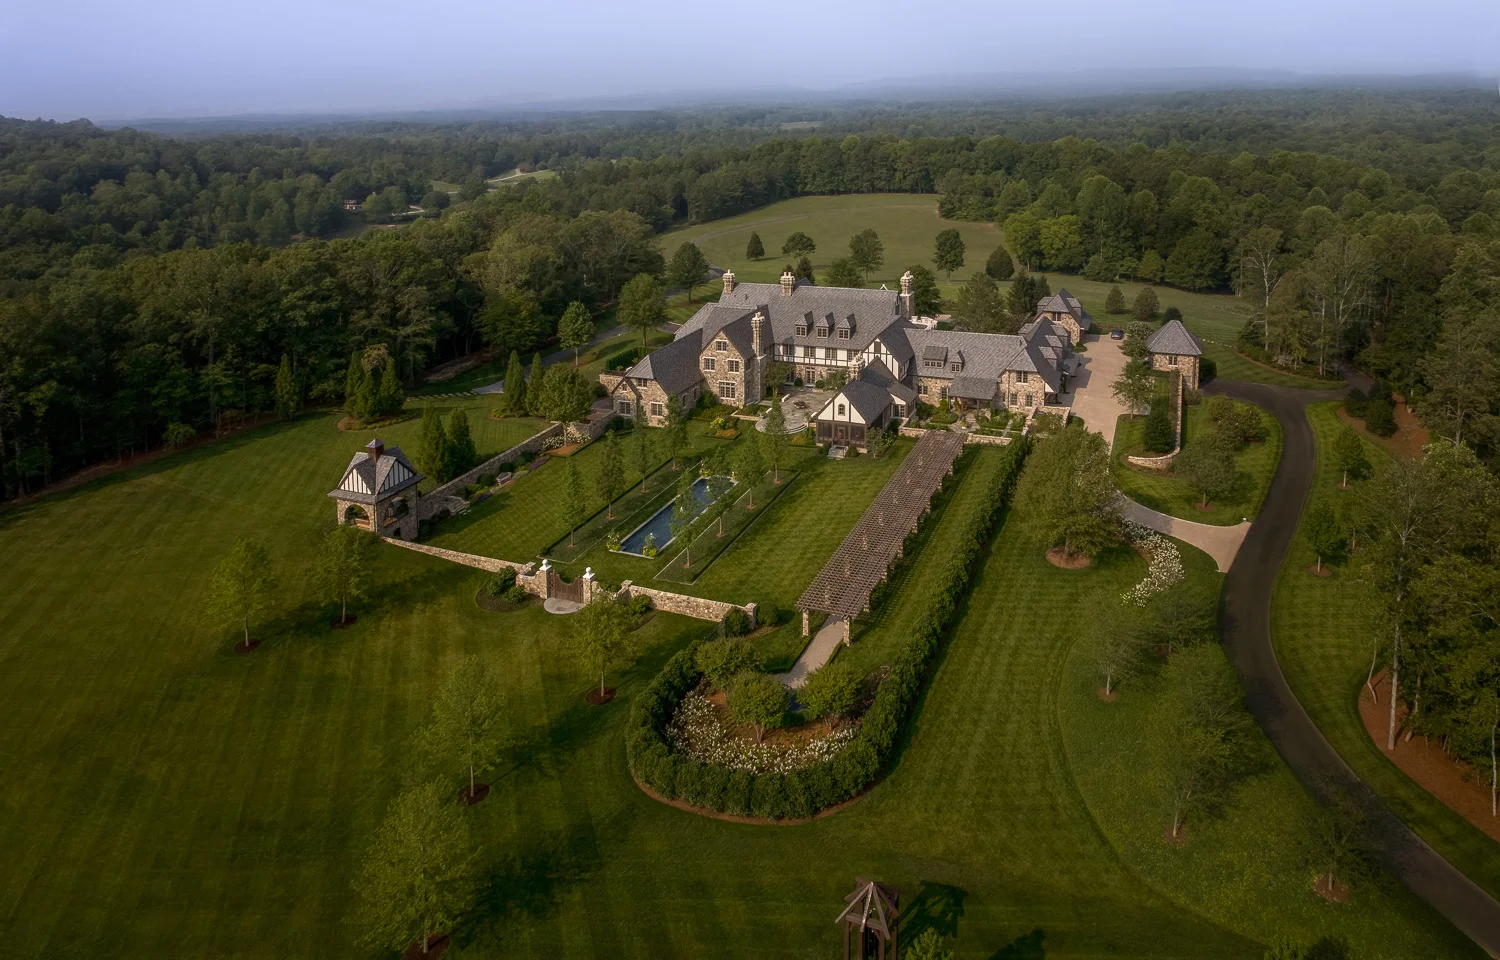
Image source: William T. Baker
How to Handle the Physical Contents of an Estate
When an estate must be closed due to death, divorce, or downsizing, the physical contents—furniture, clothing, tools, and collectibles—must be liquidated. This is often handled through an estate sale.
Professional estate liquidators provide a comprehensive service that includes sorting, pricing, marketing, and conducting the sale. However, this expertise comes at a cost. According to Charles Schwab , professional liquidators typically charge a 35% to 40% contingency fee . This fee covers the labor-intensive process of staging the home and researching the value of items. Many top-tier liquidation companies will not even take a contract unless the estimated value of the inventory meets a minimum threshold, often $10,000.
Real Estate Agent Secrets for Selling an Estate Quickly
Selling the physical house within an estate requires a different strategy than a standard home sale. Because these homes are often vacant or filled with "dated" furniture, agents use specific tricks to drive up the perceived value.
One such technique is the "30-Minute Rule." Professional agents often place portable alarms or specific showing instructions that require buyer agents to call at least 30 minutes before arriving. This gives the listing agent (or a local helper) time to rush to the property to turn on all lights, adjust the temperature, and even spray a neutral scent. This "staging of the experience" ensures the home never feels cold or abandoned, which can lead to low-ball offers.
Additionally, "depersonalizing" the estate is non-negotiable. Removing family photos and religious items allows potential buyers to visualize their own lives in the space. In the competitive luxury estate market, this emotional connection is often what drives a sale price above the appraised value.
Why You Must Include Digital Assets in Your Modern Estate
In the 21st century, an estate is no longer just physical. The "Digital Estate Gap" is a growing problem where heirs are left with no access to a decedent's most valuable or sentimental assets because they weren't included in the estate plan.
A modern estate includes cryptocurrency keys, social media accounts, cloud-stored photos, and even digital storefronts or domain names. Without explicit legal permission, service providers like Google or Apple may refuse to grant access to family members due to privacy laws. To solve this, many states have adopted the Revised Uniform Fiduciary Access to Digital Assets Act (RUFADAA) . This law allows you to name a "digital executor" who has the legal authority to manage your online presence after you are gone. Failing to account for these assets can result in the permanent loss of family history and significant financial value.
Key Takeaways for Managing an Estate
Managing an estate is a complex task that requires balancing legal requirements, financial goals, and emotional realities. Whether you are an heir or a planner, keep these points in mind:
- Identify probate vs. non-probate assets immediately to understand what will be delayed by court processes.
- Verify beneficiary designations on all financial accounts, as these will override whatever is written in your Will.
- Account for digital assets including crypto keys and cloud storage to prevent the loss of digital property.
- Expect a 35-40% fee if hiring a professional estate liquidator for physical belongings.
- Use Fair Market Value (FMV) for appraisals rather than asking prices found on the internet.
- Consult a professional for advanced tax-shielding strategies like Dynasty Trusts or GRATs if your estate is large.
- Implement the 30-minute rule when selling an estate property to ensure it is always shown in its best light.
Start by creating a comprehensive inventory of your assets and liabilities today to ensure your estate is organized for the future.
Frequently Asked Questions